How Can You Generate Monthly Income After Retirement Without Running Out of Money?
Turn your retirement savings into a dependable income stream. Understand SWP, SCSS, Post Office MIS, NPS annuities, safe withdrawal rates and inflation, with practical examples.
Key Takeaways
- The challenge is not just building a corpus. It is converting it into dependable income without exhausting it too early.
- First calculate the shortfall between your expenses and reliable income, then plan how to fund it.
- No withdrawal rate is safe for everyone. Inflation, returns and retirement length all matter.
- Combine pension, deposits, NPS annuity and market-linked investments instead of relying on one source.
Your Salary Stops, but Your Expenses Do Not
Imagine working for 30 or 35 years, saving a portion of your salary every month, investing for the future and finally reaching retirement.
You have accumulated a reasonable amount of money. Your home may be fully paid off, your children may be financially independent, and you are ready to enjoy a more relaxed life. But one important question remains: how will you pay your monthly expenses when your salary stops?
You still need money for groceries, electricity, medicines, insurance, transport and other household expenses. You may also want to travel, spend time with your grandchildren or support family members when necessary.
The challenge is not simply to accumulate a large retirement corpus. It is to convert that money into a dependable income stream without exhausting it too early.
A simple illustration
Suppose you retire with ₹1 crore in savings. Ignoring investment returns, taxes and inflation:
But real retirement planning is more complicated. Your investments may generate returns, prices may rise, and unexpected medical expenses may require additional withdrawals. Poor investment returns early in retirement can also damage the long-term sustainability of your savings.
Create a retirement income plan that balances regular spending, financial security, inflation protection and the possibility of living longer than expected. Here is how Indian retirees can approach that challenge.
1. Calculate How Much Monthly Income You Actually Need
Before choosing an investment or pension product, determine how much money your household will need every month. Your retirement income requirement should reflect your expected lifestyle rather than your salary before retirement.
For example, if your take-home salary before retirement was ₹80,000 per month, you may not need exactly ₹80,000 every month after leaving work. Some expenses may disappear, while others may increase. Start by dividing your expenses into three categories.
Costs you need to meet regardless of lifestyle choices: groceries and household necessities; electricity, water, telephone and internet; housing maintenance or rent; medicines and healthcare; insurance premiums; transport and essential travel; support for dependants; other unavoidable bills.
Expenses that make retirement enjoyable but can be adjusted when necessary: holidays and travel, dining out, entertainment and hobbies, gifts for family members, personal shopping.
Costs that do not occur every month but can significantly affect your savings: home repairs, vehicle maintenance, medical procedures, annual insurance premiums and family emergencies. Estimate their annual cost and set aside money accordingly.
Example: a retired household with ₹40,000 in monthly expenses
| Expense category | Monthly budget |
|---|---|
| Groceries and household essentials | ₹10,000 |
| Utilities and communication | ₹2,000 |
| Healthcare and medicines | ₹5,000 |
| Transport | ₹3,000 |
| Housing maintenance and insurance | ₹5,000 |
| Personal and family expenses | ₹5,000 |
| Travel and leisure | ₹5,000 |
| Provision for irregular expenses | ₹5,000 |
| Total monthly requirement | ₹40,000 |
An illustrative budget, not an average for every Indian household. Your expenses depend on location, housing, medical needs and family responsibilities.
Once you know your expected monthly requirement, you can estimate how much income must come from pensions, interest, investments or other sources.
2. Combine Different Sources of Retirement Income
One of the common mistakes in retirement planning is relying entirely on one investment or one source of income. A more flexible approach is to understand what each source can contribute. Possible sources include:
- Employer or government pension, where applicable
- National Pension System (NPS) annuity income
- Interest from eligible bank deposits
- Senior Citizens' Savings Scheme (SCSS) interest
- Post Office Monthly Income Scheme (MIS) interest, subject to eligibility and limits
- Systematic withdrawals from mutual fund investments
- Rental income, if reliable and appropriate
- Other financial assets and retirement benefits
These sources work differently. Some offer contractual or scheme-defined payments, while others depend on market performance or rental conditions.
An eligible retiree might receive a pension of ₹15,000 per month and need another ₹25,000 to meet total expenses of ₹40,000. The investment portfolio would need to help cover that remaining ₹25,000, subject to the retiree's other income, assets and financial goals. Calculate the gap between your expenses and reliable income, then decide how to fund it sustainably.
3. Understand the Systematic Withdrawal Plan (SWP)
A Systematic Withdrawal Plan, commonly called an SWP, allows an investor to withdraw a specified amount from a mutual fund at regular intervals. For example, you could arrange for ₹20,000 to be withdrawn every month from a mutual fund investment.
The withdrawal is paid from the investment, and the remaining units continue to be invested. Their value may rise or fall depending on the performance of the underlying investments. An SWP can therefore provide a regular cash flow, but it does not guarantee a fixed return or ensure that the original corpus will last throughout retirement.
How does an SWP work?
Suppose you have ₹50 lakh invested in mutual funds and arrange a monthly withdrawal of ₹20,000. Your annual withdrawals would total ₹2.4 lakh, equivalent to 4.8% of the initial corpus.
However, 4.8% is not necessarily a sustainable withdrawal rate for every portfolio or retirement period. The outcome depends on investment returns, volatility, inflation, taxes, fees and the amount withdrawn over time. If the investments perform poorly while you continue withdrawing money, you may have to sell more units to fund the same payment. That can reduce the amount remaining for future years.
Is an SWP the same as earning interest?
No. With a bank deposit, interest is calculated according to the deposit's terms. With an SWP, the withdrawal comes from mutual fund units. Some of the withdrawal may effectively represent a return of your own invested capital rather than investment profit.
An SWP should not be described as guaranteed monthly income, even when the withdrawal amount is fixed.
Who might consider an SWP?
An SWP may be worth evaluating if you have retirement savings invested in mutual funds, need regular withdrawals and understand the associated market risks. It is important to choose an appropriate investment allocation and maintain enough accessible money for near-term expenses. For official investor education, visit SEBI Investor.
4. Consider Senior Citizens' Savings Scheme and Other Deposit-Based Options
Not every retiree wants their entire savings exposed to market fluctuations. India offers several savings products that may provide periodic interest payments, subject to eligibility, deposit limits and scheme rules.
A government-backed small-savings scheme for eligible senior citizens and certain other eligible retirees under the applicable rules. It has a defined tenure and pays interest quarterly, so it is not a monthly-payout scheme. Check the interest rate, investment limits, eligibility, extension provisions and taxation before investing.
Designed to provide monthly interest income under its applicable terms. It may suit eligible investors who want scheduled interest payments. However, investment limits and tenure apply, and the monthly interest may not keep pace with inflation.
Can offer interest income according to the selected deposit and payout terms. Compare the interest rate, tenure, premature withdrawal conditions, taxation and applicable deposit insurance before investing.
The Deposit Insurance and Credit Guarantee Corporation generally insures eligible bank deposits up to ₹5 lakh per depositor per insured bank, including principal and interest, in the same right and capacity. This limit applies across eligible accounts at that bank rather than separately to each account.
Check current rates before investing
India Post publishes official information on its small-savings schemes, including SCSS and MIS. The rates displayed on its website can change when the government revises applicable rates. Check the latest terms directly at India Post Savings Schemes.
A deposit-based income strategy can provide greater predictability than relying entirely on market-linked withdrawals. However, the income may be insufficient to cover all expenses, especially when inflation rises.
5. Consider NPS Annuity Income if You Need Regular Pension Payments
The National Pension System (NPS) is a retirement-oriented savings system regulated by the Pension Fund Regulatory and Development Authority (PFRDA). Eligible subscribers may use the applicable retirement proceeds to purchase an annuity that pays a regular income under the selected terms.
An annuity can provide a useful form of retirement income, particularly for people who value predictable payments over retaining complete control of the invested amount. However, annuity products differ in their terms. Depending on the option selected, payments may continue for the annuitant's lifetime, a spouse may receive continuing payments, or a purchase-price return feature may apply. These features affect the payment amount and what happens after the annuitant dies.
What should you consider before purchasing an annuity?
- The monthly pension offered for the purchase amount
- Whether payments continue for your lifetime
- Whether a spouse is covered
- Whether the purchase price is returned to a nominee
- The impact of inflation on a fixed payment
- Tax treatment and applicable withdrawal rules
- The effect of committing money to a product with limited liquidity
Annuity income can provide predictability, but a fixed nominal payment may buy less over time as prices rise. For official information, see PFRDA's Annuity Service Provider guidance.
6. How Much Can You Withdraw Without Running Out of Money?
This is the most important question in retirement income planning. A large retirement corpus can still be depleted if withdrawals are too high relative to the money available and the returns earned. Consider a person with ₹1 crore in retirement savings. The table shows the first year's withdrawal under different illustrative annual withdrawal rates.
| Initial withdrawal rate | Annual withdrawal | Monthly equivalent |
|---|---|---|
| 2.5% | ₹2.5 lakh | About ₹20,833 |
| 3% | ₹3 lakh | ₹25,000 |
| 4% | ₹4 lakh | About ₹33,333 |
| 5% | ₹5 lakh | About ₹41,667 |
| 6% | ₹6 lakh | ₹50,000 |
Arithmetic illustrations based on the initial corpus. They are not guarantees of sustainable income.
A 4% initial withdrawal rate, for example, does not mean every retiree can safely withdraw 4% every year for the rest of their life. The result depends on the investment portfolio, retirement duration, inflation adjustments, taxes and market conditions.
If you withdraw ₹50,000 every month from a ₹1 crore corpus, your initial annual withdrawal is 6% of the corpus. That may put considerable pressure on the portfolio if the retirement period is long or returns are weak.
Why withdrawing too much early can be dangerous
Imagine that the market falls during the first few years of your retirement. You still need to pay your bills. If you sell investments to fund withdrawals while their value is depressed, fewer assets remain to participate in any later recovery.
The order in which investment returns occur can matter significantly when you are withdrawing money from your portfolio. A retirement plan should test not only the average expected return but also what could happen during an extended period of weak markets.
7. Inflation: Your Monthly Retirement Income Must Change Over Time
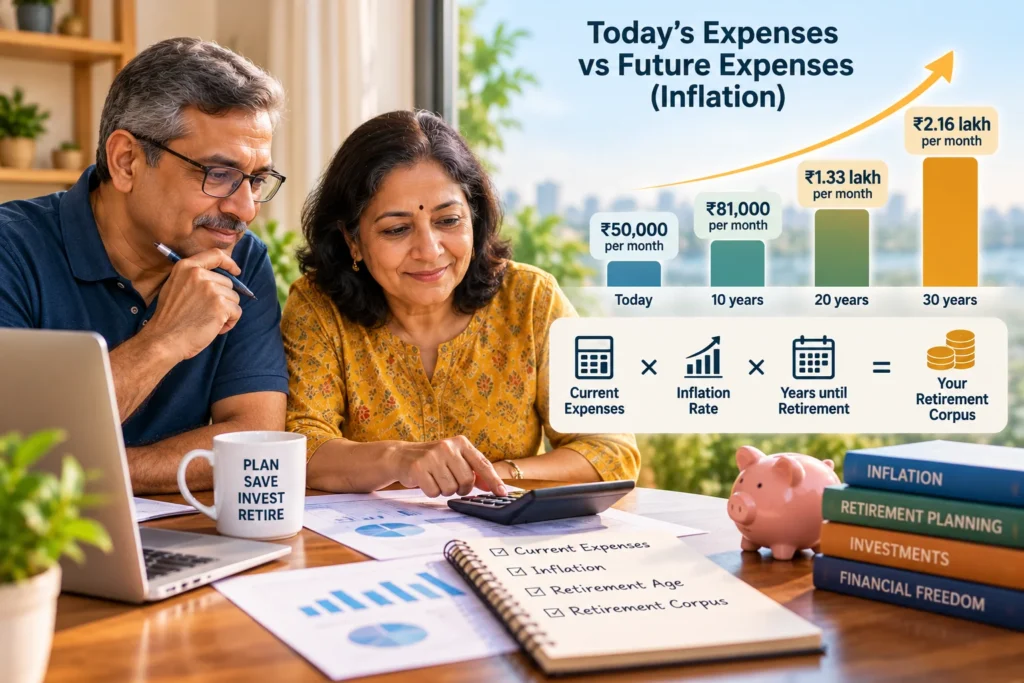
Suppose your monthly expenses are ₹40,000 when you retire. If inflation averages 5% per year, your monthly expenses could rise to approximately ₹65,200 after 10 years and ₹1.06 lakh after 20 years.
| Time after retirement | Monthly expenses at 5% inflation |
|---|---|
| At retirement | ₹40,000 |
| After 5 years | About ₹51,000 |
| After 10 years | About ₹65,200 |
| After 20 years | About ₹1.06 lakh |
Assumes constant annual inflation of 5%. Actual expenses may grow at different rates.
This creates a challenge for retirees who rely only on fixed nominal interest income. A monthly interest payment of ₹20,000 may be useful today, but its purchasing power could decline considerably over a long retirement.
This does not mean you should expose all your savings to market risk. Instead, your plan should balance near-term stability with the need to preserve purchasing power over time. That may involve combining relatively stable income sources with a suitable long-term investment portfolio, depending on your circumstances and risk tolerance.
8. A Practical Example: Generating ₹40,000 Monthly Income After Retirement
Suppose a retired household needs ₹40,000 per month and receives ₹15,000 per month from a reliable pension, leaving a monthly shortfall of ₹25,000.
That calculation can provide a starting point, but it does not prove that the corpus will last for the entire retirement period. The household would still need to consider:
- Whether the pension increases over time
- Whether expenses rise with inflation
- How the remaining corpus is invested
- Whether withdrawals can be reduced during difficult market periods
- Whether additional healthcare expenses are likely
- Whether the household wants to preserve money for a spouse or heirs
The household might compare an SWP with interest-bearing products and other eligible retirement income options. The final arrangement should reflect the family's need for liquidity, stability, growth and flexibility.
Calculate the shortfall after reliable income first, then plan how to meet it.
9. Five Ways to Reduce the Risk of Running Out of Money
Maintain a reserve for near-term expenses
Keep money for immediate household needs and foreseeable expenses in an accessible, relatively stable form. This can reduce the need to sell long-term investments during a market downturn.
Diversify your retirement resources
Avoid relying entirely on one investment or one income source. A combination of pension income, eligible deposits and suitable investments may help balance predictability, liquidity and long-term growth. Diversification does not eliminate risk, but it can reduce dependence on a single source.
Review withdrawals regularly
Your expenses, investment values and income sources will change over time. Review your withdrawal amount at least annually and after major financial changes. If the portfolio falls sharply, consider whether discretionary expenses can be reduced temporarily.
Prepare for healthcare costs
Medical expenses can be substantial, particularly during later retirement years. Review your health insurance and maintain an appropriate reserve for costs that insurance may not cover.
Avoid chasing unusually high returns
Retirement savings may need to support you for decades. Be cautious about products promising unusually high or guaranteed returns. Understand the risk, liquidity, costs and regulatory status before investing.
10. Frequently Asked Questions
How can I generate monthly income after retirement in India?
Possible sources include an eligible pension, NPS annuity income, interest from deposits, SCSS, Post Office MIS and withdrawals from suitable investment portfolios. The right combination depends on your age, assets, income needs, risk tolerance and applicable eligibility rules.
Can I live off the interest from ₹1 crore?
It depends on the interest rate, taxes, inflation and your monthly expenses. Interest income may cover some or all of your needs, but spending all the interest without considering inflation may reduce your purchasing power over time.
Is an SWP safe for retirement income?
An SWP is a withdrawal facility, not a guaranteed income product. Its sustainability depends on the underlying investments, withdrawal amount, market performance, taxes and retirement duration.
How much should I withdraw from my retirement corpus each month?
There is no universal withdrawal amount that works for everyone. Start by estimating the shortfall between expenses and other reliable income. Then test different withdrawal rates against your retirement horizon, inflation assumptions and investment risks.
Is SCSS better than a mutual fund SWP?
They serve different purposes. SCSS has scheme-defined terms and quarterly interest payments for eligible investors, while an SWP withdraws money from a market-linked mutual fund investment. Compare liquidity, risk, payout frequency, inflation exposure, taxation and eligibility rather than assuming one is always better.
Will a fixed monthly pension be enough for my entire retirement?
It may cover a portion of your expenses, but inflation can reduce its purchasing power if payments do not increase. Review whether you need additional income or investments to support rising costs.
Should I keep all my retirement savings in fixed deposits?
Not necessarily. Fixed deposits can provide defined interest payments, but a portfolio held entirely in deposits may face inflation and reinvestment risks. Your allocation should reflect your income needs, risk tolerance, liquidity requirements and retirement duration.
How often should I review my retirement income plan?
Review it at least once a year and whenever there is a significant change in expenses, investment values, health, family circumstances or income sources.
Conclusion: Build a Retirement Income Plan, Not Just a Retirement Corpus
Retirement security is not determined solely by how much money you accumulate. It also depends on how effectively you turn those savings into income and how carefully you manage withdrawals over time.
Start by calculating your essential monthly expenses. Subtract any reliable pension or other income, then determine how much additional income your investments must provide. Compare suitable income sources, understand their risks and keep enough accessible money for immediate needs. Review your withdrawal strategy regularly, account for inflation and avoid assuming that any investment can guarantee lifelong financial security.
You may not be able to predict every expense or market movement. However, you can build a plan that is flexible enough to respond when circumstances change. The aim is not to spend as little as possible during retirement. It is to enjoy the retirement you have worked for while giving your savings a realistic chance of supporting you for as long as you need them.
Take the Next Step Towards Retirement Security
Generating monthly income after retirement is one part of financial planning. Estimating your retirement corpus, building an emergency fund and understanding inflation are equally important. Explore our personal finance guides to learn how to calculate your retirement needs, manage household expenses and make informed decisions about long-term savings. For a personalised retirement income strategy, consider consulting an appropriately qualified financial professional.
Explore Our Financial Guides →Sources and Further Reading
- SEBI Investor: Plan Early for Retirement
- India Post: Savings Schemes
- PFRDA: Annuity Service Providers
- PFRDA: National Pension System
- SEBI: Investor Education